Last updated: October 2026
What Is the Overtime Tax Deduction?
The overtime tax deduction is a temporary federal tax break for workers who are paid overtime required by federal law. It comes from the One Big Beautiful Bill Act (OBBBA), often called “no tax on overtime.” It applies to tax years 2025 through 2028 only. Your overtime pay is still taxable income, so this is a deduction, not an exemption.
Want a quick number? Use our free no tax on overtime calculator to estimate your savings.
So how does the deduction work, and who qualifies? It depends on whether your overtime is required by federal law, your filing status, and your income. Here is the full breakdown.
Table of Contents
- How the Overtime Tax Deduction Works
- Who Qualifies for the Overtime Tax Deduction
- How to Calculate Your Overtime Tax Deduction
- Overtime Tax Deduction Examples by Income Level
- How to Claim the Deduction on Your Tax Return
- Common Mistakes to Avoid
- Overtime Tax Deduction vs. Overtime Tax Withholding
- Frequently Asked Questions
- Final Thoughts
How the Overtime Tax Deduction Works
This deduction doesn’t cut your tax bill directly. It lowers your taxable income, which lowers the tax you owe.
- Only overtime required by Section 7 of the Fair Labor Standards Act (FLSA) qualifies, and only the “half” portion of time-and-a-half pay.
- Your regular pay and the base “time” part of overtime are not deductible.
- You don’t need to itemize. You can take the standard deduction and still claim it.
- Overtime is still part of your gross income. It is still subject to Social Security tax, Medicare tax and income tax withholding.
- The deduction ends after tax year 2028.
“No tax on overtime” does not mean your overtime is tax-free when you earn it. Your employer keeps withholding as usual. The benefit shows up when you file Schedule 1-A with your Form 1040, usually as a lower tax bill or a larger refund.
Who Qualifies for the Overtime Tax Deduction
First, your job classification matters. The deduction covers only overtime that the FLSA requires. If you are classified as exempt, no amount qualifies, no matter how many hours you work. Hourly workers, and salaried workers classified as non-exempt, can qualify. Ask HR or payroll if you are unsure.
Other rules:
- You need a valid Social Security number.
- Married taxpayers must file a joint return. Married filing separately does not qualify.
- Qualified tips are not counted as overtime.
| Filing Status | Maximum Deduction | Phaseout Begins (MAGI) | Fully Phased Out At |
|---|---|---|---|
| Single | $12,500 | $150,000 | $275,000 |
| Married Filing Jointly | $25,000 | $300,000 | $550,000 |
The cap applies first. Then your deduction drops by $100 for every $1,000 of MAGI above the starting amount. A smaller deduction reaches $0 sooner. Only a full $12,500 deduction (single) or $25,000 deduction (joint) lasts until the ending amounts above.
For this deduction, MAGI is your adjusted gross income plus certain foreign income exclusions. For most workers, it equals AGI.
This is a federal deduction. Many states don’t automatically follow it, so state tax may still apply to your overtime.
How to Calculate Your Overtime Tax Deduction
You don’t need a tax background to estimate this. The process generally follows five simple steps:
- Confirm your overtime is required by the FLSA.
- Find your qualified premium, the “half” part. If all your overtime hours were paid at time-and-a-half, divide your total overtime pay by 3. For hours paid at double time, only the half portion counts, so divide that pay by 4.
- Add the premium for the year. It is figured each workweek. For 2026, it should match Box 12, Code TT on your W-2.
- Compare the total with the cap: $12,500 (single) or $25,000 (joint).
- Subtract $100 for every $1,000 your MAGI is above the threshold. The result can’t go below $0.
A warehouse worker earns $22/hour and works 120 overtime hours at $33/hour. The premium is $11 per hour, so qualified overtime is $1,320. With MAGI under $150,000, the full $1,320 is deductible.
Overtime Tax Deduction Examples by Income Level
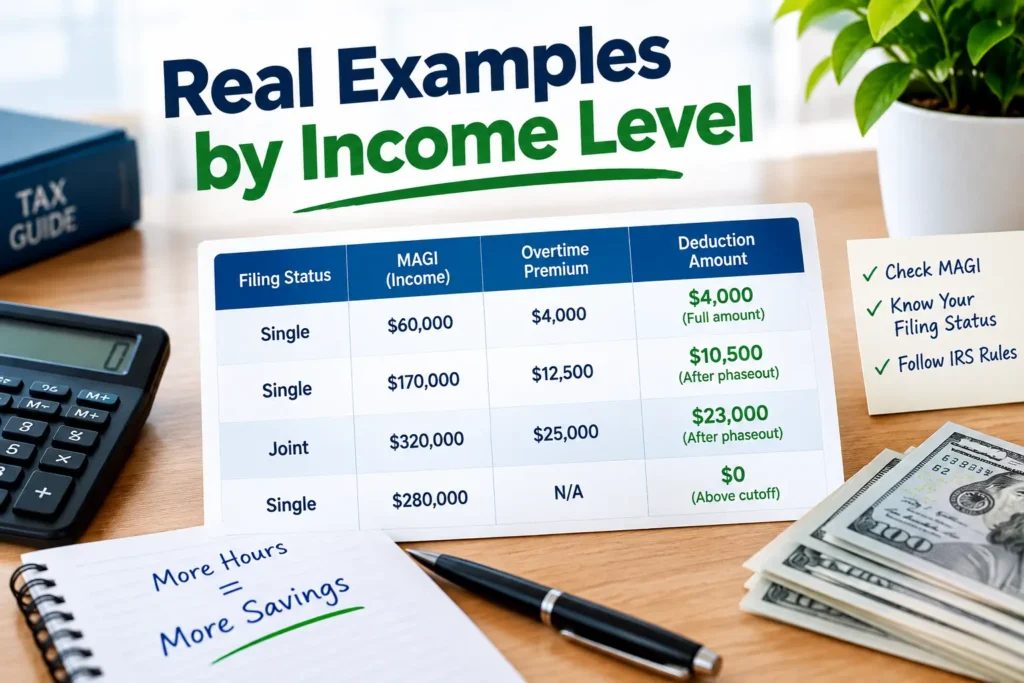
Numbers make the phaseout easier to picture than rules alone. Here’s how it plays out at a few income levels:
- Single filer, $170,000 MAGI, $12,500 qualified overtime: $20,000 over the threshold means a $2,000 reduction, leaving $10,500.
- Single filer, $185,000 MAGI, $3,000 qualified overtime: $35,000 over means a $3,500 reduction, so the deduction is $0. Smaller deductions end sooner.
- Joint filers, $320,000 MAGI, $25,000 qualified overtime: $20,000 over means a $2,000 reduction, leaving $23,000.
See more worked examples in our overtime tax deduction examples guide.
How to Claim the Deduction on Your Tax Return
Tax year 2025 returns: Employers were not required to report qualified overtime separately. The IRS allows you to figure it from pay stubs and other records using the methods in Notice 2025-69. If you already filed and missed the deduction, you may be able to amend with Form 1040-X.
Tax year 2026 and later: Employers must report qualified overtime in Box 12 of your W-2 with Code TT. You can generally deduct only the amount reported there. The Code TT figure includes all qualified overtime paid, even above the $12,500 or $25,000 cap. If it is missing or too low, ask your employer for a corrected Form W-2c. A pay stub alone is not enough.
Steps:
- Check Box 12, Code TT on your W-2 (it arrives in January 2027).
- Compare it with your final pay stub of the year.
- Confirm your MAGI for the phase-out.
- Complete Schedule 1-A and file it with your Form 1040.
- Keep pay stubs and W-2s for at least three years.
Common Mistakes to Avoid
A few recurring errors cause workers to either overclaim or miss out on this benefit entirely:
- Deducting the full overtime wage instead of just the premium above regular pay.
- Ignoring the MAGI phaseout, which quietly shrinks the deduction for higher earners.
- Skipping Schedule 1-A, since the deduction isn’t applied automatically.
- Assuming FICA taxes drop, when only federal income tax is affected.
- Filing married-separately and expecting to qualify, which the rules exclude.
- Relying on pay stub estimates for 2026 instead of the amount reported in W-2 Box 12, Code TT.
- Assuming you qualify when your job is exempt under the FLSA.
- Assuming the deduction lasts until $275,000 MAGI for everyone.
Overtime Tax Deduction vs. Overtime Tax Withholding
Withholding is the tax taken from each paycheck. The deduction is claimed on your return. Employers must keep withholding on overtime and can’t lower it unless you give them an updated Form W-4.
Want a bigger paycheck? Use Step 4(b) on the 2026 Form W-4 or the IRS Tax Withholding Estimator. For a full comparison, read overtime tax deduction vs withholding.
Frequently Asked Questions
Does the overtime tax deduction apply to all overtime pay?
No. Only overtime required by the FLSA qualifies, and only the premium part. For time-and-a-half, that is the extra half. If your employer pays double time, only the half portion required by the FLSA counts.
How much can I actually deduct?
Up to $12,500 for single filers and $25,000 for joint filers. High earners get less once MAGI passes $150,000 (single) or $300,000 (joint). Smaller deductions phase out sooner.
Will this deduction lower my paycheck withholding?
Not automatically. Employers must keep withholding tax on overtime as usual and can’t reduce it just because you may qualify for the deduction. However, you can submit an updated Form W-4 (Step 4(b) on the 2026 form) to account for the expected deduction, and the IRS Tax Withholding Estimator also factors it in. Otherwise, the benefit shows up when you file Schedule 1-A with your return, usually as a larger refund.
Does the deduction reduce Social Security or Medicare tax?
No, FICA taxes apply to overtime pay exactly as before this rule existed. Social Security and Medicare withholding are calculated the same way regardless of this deduction. Only your federal income tax liability is affected once you file. Payroll tax obligations remain completely unchanged for both you and your employer.
What happens if my income is above the phase-out limit?
Your deduction drops by $100 for every $1,000 of MAGI above the starting amount, and it can’t go below $0. A full $12,500 deduction ends at $275,000 MAGI (single). A full $25,000 deduction ends at $550,000 (joint). A smaller deduction ends sooner.
Do self-employed or 1099 workers qualify?
Generally no, because most independent contractors aren’t covered by FLSA overtime rules. If you are an employee for FLSA purposes but treated as a contractor, the payer reports qualified overtime on Form 1099-MISC or 1099-NEC starting in 2026.
Does my state also exempt overtime pay from income tax?
Not automatically. This is a federal deduction, and many states still tax overtime in full. Check your state tax agency.
What if I already filed my 2025 return without the deduction?
You may be able to claim it by filing Form 1040-X. Wait until your original return is processed, and keep the calculation you used. You generally have three years to amend.
Final Thoughts
This deduction rewards workers who earn FLSA overtime, but the real benefit depends on your classification, your premium and your income. Confirm your qualified overtime, check your MAGI, and file Schedule 1-A correctly. Since it runs only through 2028, review your situation each filing season.
Sources:
IRS Fact Sheet FS-2026-13, IRS Notice 2025-69, and 26 U.S.C. § 225. This article is general information, not tax advice.
- Notice 2025-69: https://www.irs.gov/pub/irs-drop/n-25-69.pdf
- IRC §225: https://www.law.cornell.edu/uscode/text/26/225

Hi, I’m Sultan Mehmood, founder of NoTaxOnOvertimeCalculator.net. I started this site in 2026 to make overtime pay and tax topics easy to understand. I create simple calculators and clear guides on overtime pay, tax deductions, and take-home salary.